California debt relief programs are the legitimate ways a California resident can lower, restructure, or erase credit card debt. The main ones are nonprofit credit counseling with a debt management plan, a consolidation loan or balance transfer card, debt settlement, and bankruptcy. No state or federal program simply wipes out credit card balances, so any ad that promises one deserves suspicion. The right choice depends on your credit score, how much you owe, and whether you can still afford a monthly payment.
This article covers why these programs matter, how each option works, and how to pick one using a worked example. It also shows how to tell a legitimate company from a scam and which California rules and aid programs help alongside. If you searched for credit card debt relief in California, you will find each answer here, in order of how much it matters to your decision.
Credit Card Solution is an online aid center run by people with a finance background. We don’t lend money, settle debts, or enroll you in anything ourselves. The site is funded by advertising, so our job is to explain the options and their risks plainly.
Why California debt relief programs matter
These programs matter because credit card interest compounds faster than most people can pay it down, and California’s high living costs leave little room to pay extra. Left alone, a balance at 18% to 29% APR can cost you thousands more than you borrowed. The right program cuts that interest or the balance itself.
What interest does to your payoff
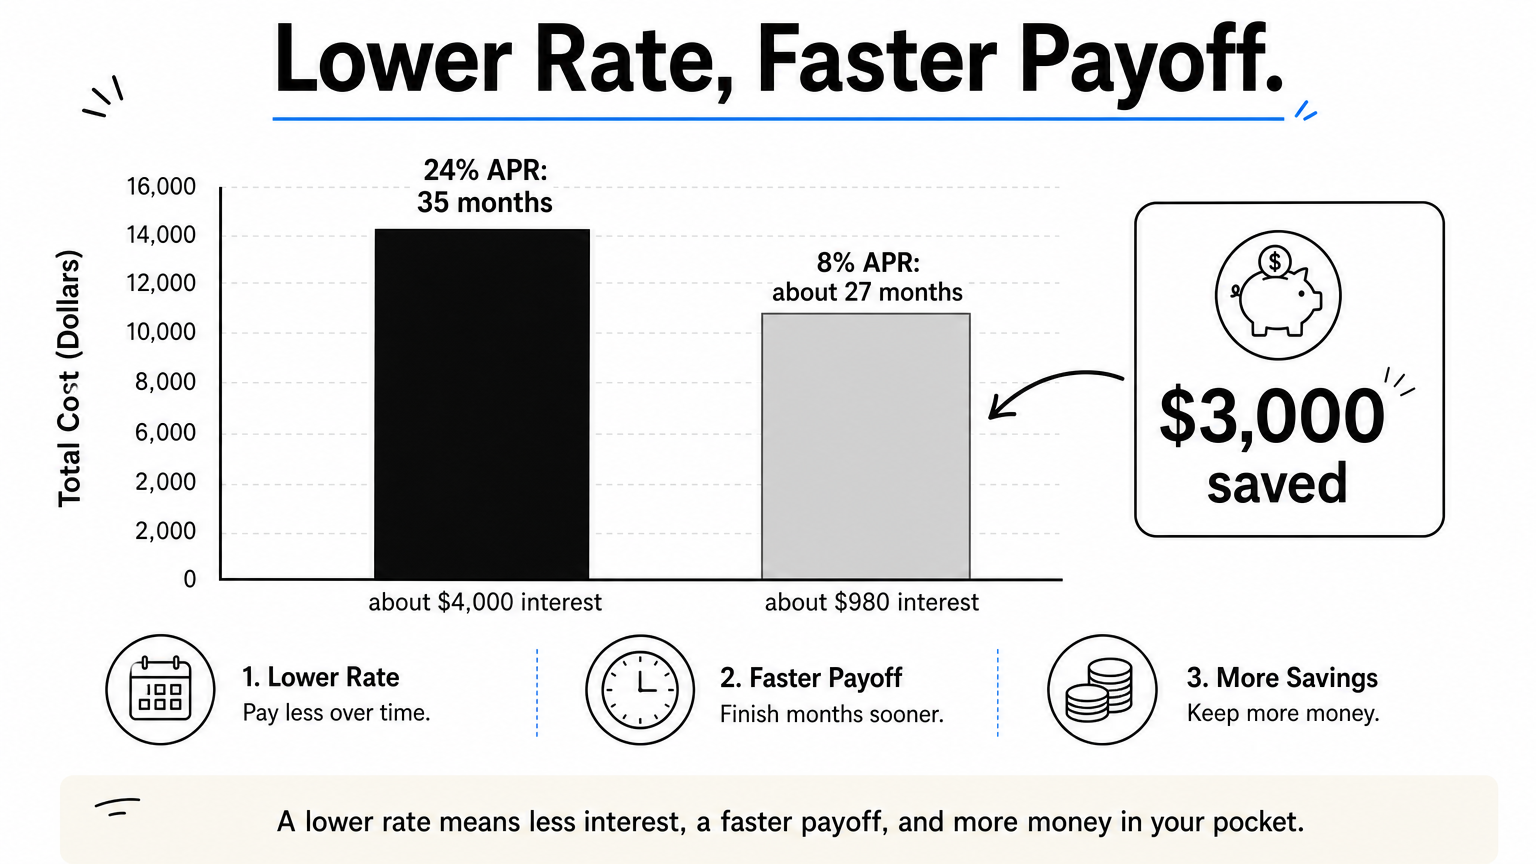
The same payment can clear a debt in very different times depending on the rate. Here is a $10,000 balance paid at a fixed $400 a month.
| Scenario | APR | Monthly payment | Months to pay off | Total interest |
|---|---|---|---|---|
| Typical card rate | 24% | $400 | 35 | about $4,000 |
| Negotiated or consolidated rate | 8% | $400 | about 27 | about $980 |
Dropping the rate saves roughly $3,000 in interest and gets you out more than 7 months sooner, with no change to your monthly payment. That gap is what every legitimate program is trying to create, whether by lowering the rate, lowering the balance, or stretching the timeline.
A lower interest rate does more for you than a bigger payment you can’t sustain.
Signs it is time to look at a program
Waiting makes most options harder. Debt management plans and consolidation loans work best before you miss payments, because late payments damage your score and shrink your choices. Consider a program if any of these describe you:
- Your balances have not dropped in six months of on-time payments.
- You use one card to pay another, or to cover groceries and rent.
- Late fees and penalty rates are stacking up.
- Collectors have started calling.
If two or more apply, move on to the options below. If you are already missing payments, speed matters even more.
The main debt relief options for California residents
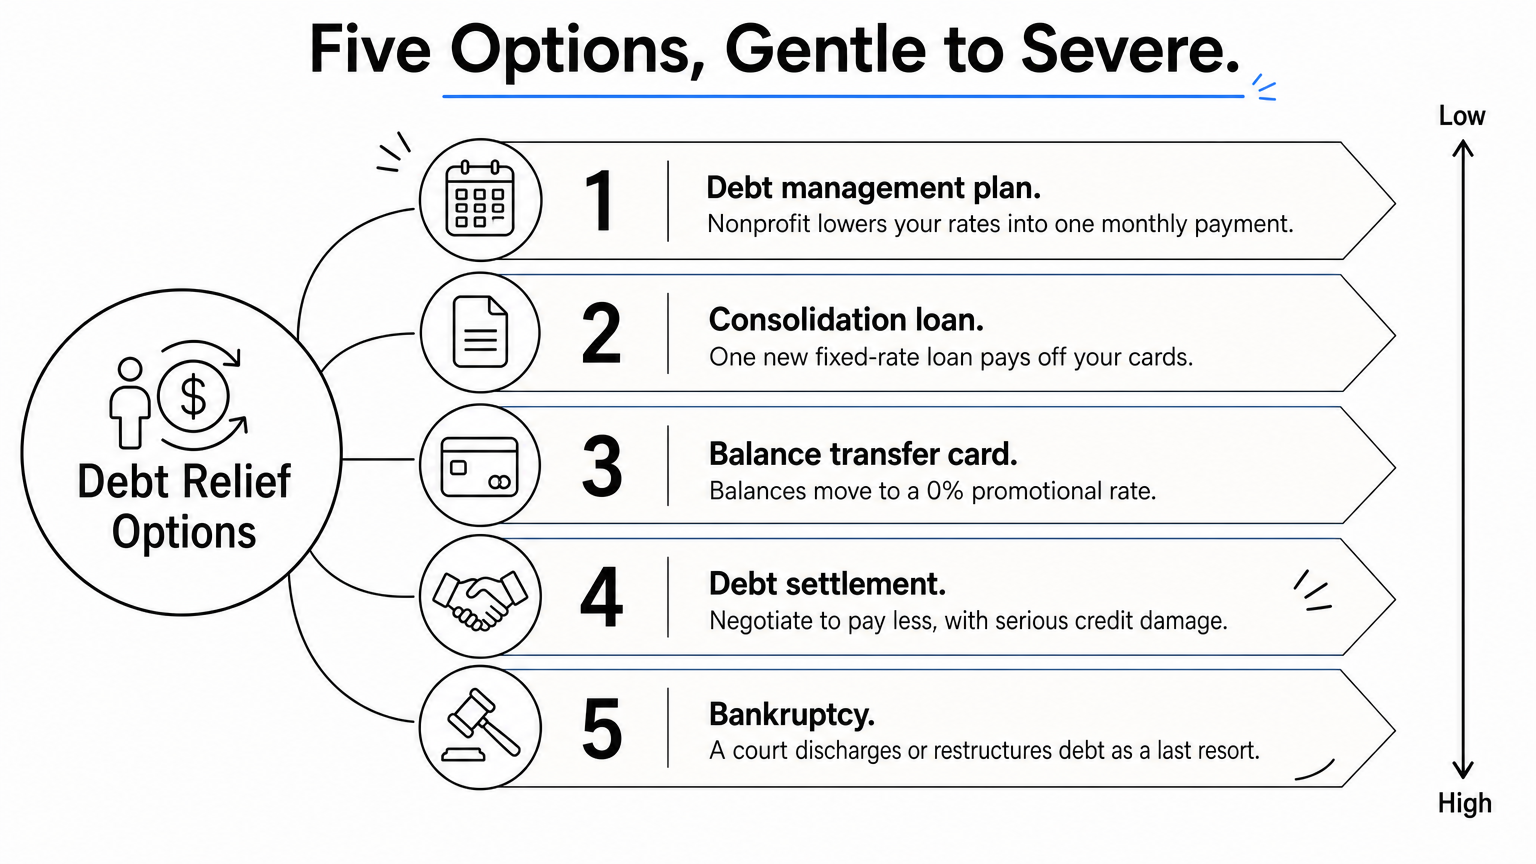
There are five main options. They run from gentle and low-risk to severe and last-resort, and they differ in cost, timeline, and credit damage. Here is how each works and where each one fits.
Debt management plans through nonprofit counseling
A debt management plan (DMP) is run by a nonprofit credit counseling agency. A counselor reviews your budget, then negotiates lower interest rates with your card issuers. You make one monthly payment to the agency, which distributes it to your creditors.
Plans usually take 3 to 5 years, and your credit score generally isn’t a qualifying factor. The trade-offs are that enrolled cards are typically closed and you must keep paying on schedule. Many agencies offer a free first session, so you can get a budget review without committing.
Consolidation loans and balance transfer cards
A consolidation loan pays off your cards with one new loan at a fixed rate and term. A balance transfer card moves your balances to a 0% promotional APR, usually for 12 to 21 months, for a transfer fee that is typically 3% to 5%. Both depend on your credit.
They work best with scores around 700 or higher and a plan to pay off the balance during the promotion or loan term. With weaker credit, the rate you are offered may not beat what you already pay.
Debt settlement
Debt settlement means paying a creditor less than you owe. Settlement companies usually tell you to stop paying your cards and deposit money into a separate account until there is enough for an offer. Meanwhile, late fees and penalty interest pile up, and creditors can sue.
The Consumer Financial Protection Bureau warns that settlement can leave you deeper in debt. Not every creditor cooperates, and missed payments stay on your credit report for seven years. Treat debt settlement as a late-stage choice, not a first move.
Bankruptcy
Bankruptcy is a legal process that discharges or restructures debt. In Chapter 7, you generally need income below the state median for your household size (or must pass a means test). Non-exempt assets can be sold, though California lets you choose between two sets of exemptions that protect most people’s home, car, and tools of trade.
In Chapter 13, you keep your assets and follow a 3 to 5 year repayment plan. A filing stays on your credit report for 7 to 10 years. A bankruptcy attorney can tell you which chapter fits, and many offer a free first consultation.
Side-by-side comparison
This table sets the five options next to each other.
| Option | How it works | Typical timeline | Credit impact | Best fit |
|---|---|---|---|---|
| Debt management plan | Nonprofit negotiates lower rates; one monthly payment | 3 to 5 years | Cards usually closed; on-time payments help over time | Fair or damaged credit, steady income |
| Consolidation loan | New loan pays off cards | Fixed term set by lender | Hard inquiry, then improves as balances fall | Good credit, roughly 700+ |
| Balance transfer card | Balances move to a 0% promo APR | Promo often 12 to 21 months | Hard inquiry; 3% to 5% fee | Good credit, can pay off within promo |
| Debt settlement | Negotiate to pay less than owed | Often 2 to 4 years | Severe; late marks stay 7 years | Large debt, payments unaffordable |
| Bankruptcy | Court discharges or restructures debt | Chapter 7: months; Chapter 13: 3 to 5 years | Severe; 7 to 10 years on report | Debt cannot realistically be repaid |
Start with the gentlest option your credit qualifies for, and move down the table only when it fails.
How to choose the right program for your debt
Choose by matching your credit score, your total debt, and your monthly cash flow to the options above. Start with the least damaging one that you qualify for and can afford, and only move to harsher options when the gentler ones are out of reach.
Match the option to your credit profile
Use these rules of thumb as a starting point:
- Score around 700 or higher, steady income: a balance transfer card or consolidation loan. Run the numbers on fees before you commit.
- Score in the 600s or below, steady income: a nonprofit debt management plan, since credit score generally isn’t a qualifying factor.
- Debt you can’t repay even with a lower rate: talk to a bankruptcy attorney before considering settlement. Compare bankruptcy or debt settlement honestly.
- Manageable debt and strong discipline: pay off your credit card debt yourself. List cards by interest rate, pay minimums on all, and put every extra dollar on the highest rate. Ask each issuer for a lower APR.
A worked example: $14,000 across three cards
Say you owe $14,000 at an average 24% APR and your score is 640. A balance transfer card is unlikely to approve you for that amount. Paying the debt off over 60 months at 24% costs about $403 a month and about $10,160 in interest.
Now assume a nonprofit agency negotiates an average 8% rate. Over the same 60 months, the payment drops to about $284, and interest falls to about $3,030. You save around $119 a month and about $7,100 in total. The 8% figure is an assumption, and actual rates vary by creditor, so ask any agency for the specific rate it expects.
Steps to take this week
- List every card with its balance, APR, and minimum payment.
- Subtract essential spending from your take-home pay to see what you can truly put toward debt.
- Pull your free credit reports and check your score.
- Book a free session with a nonprofit credit counselor to compare a plan against paying it yourself.
- Get any plan or fee schedule in writing and read it before you agree.
If you can afford the payment on a lower rate, you almost never need settlement or bankruptcy.
How to tell a legitimate program from a scam
A legitimate program charges fees only after it delivers a result, makes no guarantees, and tells you plainly what it will do to your credit. If a company breaks any of those rules, walk away. The question "is California debt relief a legitimate program?" has no single answer because it isn’t one program. It is a label that honest nonprofits and predatory companies both use.
Red flags that should end the conversation
The CFPB lists the warning signs. Avoid any company that:
- Charges fees before it settles any of your debts.
- Promises to settle all your debts for a set percentage reduction.
- Guarantees your debt will go away, or can be paid off "for pennies on the dollar."
- Advertises a "new government program" to bail out credit card debt.
- Tells you to stop communicating with your creditors.
- Claims it can stop all collection calls and lawsuits.
The second point answers a common question. No government program forgives credit card debt, so a company claiming one is lying or misleading you.
A fee charged before any debt is settled is the clearest sign of a bad actor.
How to verify a company before you pay
First, ask whether it is a nonprofit and whether its counselors are certified. Many reputable agencies are accredited through the National Foundation for Credit Counseling. For bankruptcy, federal law requires credit counseling from an approved agency before you file, so that step is routine.
Second, check the company with California’s Department of Financial Protection and Innovation. The DFPI regulates debt settlement services in the state and takes complaints. Third, get every fee and monthly cost in writing, and ask what happens to your accounts if you stop paying. A company that dodges those questions has answered them for you.
California rules and aid that work alongside a program
California gives you protections against abusive collectors and several aid programs that free up cash. None of them erase credit card debt, but they can make a plan affordable or keep a collector from making things worse.
Collection rules that protect you
The state’s Rosenthal Fair Debt Collection Practices Act sets conduct rules for collectors, and the federal Fair Debt Collection Practices Act adds its own. Debt collectors in California must also be licensed by the DFPI under the Debt Collection Licensing Act. If a collector contacts you, you can dispute the debt in writing within 30 days of the first notice and ask for validation. Keep copies of everything you send and receive.
Aid programs that free up monthly cash
Cutting essential bills leaves more for debt. Depending on your income, you may qualify for CalFresh food benefits, Medi-Cal health coverage, CARE or FERA utility discounts, and LIHEAP energy bill help. Your county social services office and utility can tell you what you qualify for.
Don’t confuse these with credit card relief. The state’s Debt Reduction Program, for example, is for child support debt owed to the government and has nothing to do with credit cards.
Taxes on forgiven debt
If a creditor cancels $600 or more, it generally reports the amount to the IRS, and the canceled debt may count as taxable income unless an exception such as insolvency applies. This matters most with settlement. Ask a tax professional how it applies to you before you settle.
Aid programs won’t clear your cards, but they can make the payment on a good plan possible.
Where to start
California debt relief programs are tools for cutting interest or balances, and the right one depends on your credit and cash flow. Try a nonprofit debt management plan, a consolidation loan, or a balance transfer first. Treat settlement and bankruptcy as last resorts. Check any company for upfront fees and false guarantees, and verify it with the DFPI before you send money.
You can do the first step today: list your cards, count your spare cash, and book a free counseling session. For more help comparing options and getting out of credit card debt, see how debt relief programs affect your credit, option by option.