The best credit card to get out of debt is a balance transfer card with a long 0% intro APR, because every payment goes to the balance instead of interest. If your credit is good, that is your pick. If you need more time than a promo offers, a low-APR card fits better. If your credit is damaged, no card will clear the debt, and a secured card only supports a different payoff plan.
Most people with card debt pay 18% to 29% interest, so a large part of each minimum payment disappears into interest. A card can fix that only if it lowers your rate and you stop adding new charges. Credit Card Solution is an educational site, not a lender or card issuer, so this list ranks card types and shows the math instead of pushing one product.
Below you will find five card types in order of how well they work for paying off existing debt. Each one covers how it works, what it costs, who should use it, and a payoff example.
1. Long 0% intro APR balance transfer card
This is the strongest option for good credit. You move balances onto a card that charges 0% interest for 12 to 21 months, so your whole payment attacks the principal.
How it works and what it costs
You apply, get approved, then ask the issuer to pay off your old cards. The new card charges no interest on transferred balances during the promo window, but it does charge a one-time fee. Check these terms before you apply:
- Intro period: typically 12 to 21 months
- Transfer fee: usually 3% to 5% of the amount moved
- Limit: your new credit limit caps how much you can move, and you generally cannot transfer between cards from the same issuer
- After the promo: any leftover balance jumps to the regular APR, often 18% to 29%
Who it suits and how to use it
This card suits you if your credit is good, usually a score around 670 or higher, and you can pay the balance off inside the promo window. Divide the total moved, fee included, by the number of promo months, then set autopay for that amount. Keep paying minimums on the old cards until the transfer posts, since transfers can take a couple of weeks.
| Balance | Fee | Total to repay | Months | Monthly payment |
|---|---|---|---|---|
| $6,000 | 3% ($180) | $6,180 | 21 | $294.29 |
| $6,000 | 5% ($300) | $6,300 | 21 | $300.00 |
| $10,000 | 3% ($300) | $10,300 | 6 | $1,716.67 |
Compare that with leaving $6,000 on a 24% card, which costs about $120 in interest in the first month alone. A $30,000 balance in 12 months needs about $2,575 a month, and few cards offer a limit that high, so you would probably split it across two cards. Never charge new purchases to the card, and never miss a payment, because a late payment can end the promo rate.
A 0% transfer card works only if you divide the balance by the promo months and pay that amount on autopay.
2. Low-fee or no-fee balance transfer card
A card with a reduced or zero transfer fee is the best pick when your balance is small and you can pay it off quickly. The fee is the real cost of a transfer, so a small balance with a short timeline can make a cheaper fee matter more than a longer promo.
How it works and what it costs
It works like any transfer card, but the issuer trades a lower fee for a shorter or less generous offer. Some issuers charge a reduced fee on transfers made in the first months, then raise it. Read the fee schedule and the transfer deadline, because the cheap fee often expires. The intro period can also be shorter than on cards with a 3% to 5% fee.
Who it suits and how to use it
Choose this card if you owe around $1,000 to $4,000 and can clear it in under a year. On $3,000, a 5% fee costs $150, a 3% fee costs $90, and a zero fee costs nothing. A 0% fee over 10 months means $300 a month with no extra cost. If you can’t finish inside the promo, the savings on the fee do not make up for the interest on what is left.
On small balances you can clear fast, the fee decides your savings more than the length of the promo.
3. Low ongoing APR card
A card with a permanently low rate is the right choice when you need more than 21 months. You never face a rate cliff, so a longer payoff stays predictable.
How it works and what it costs
Instead of a promo, you get a lower standing APR, often from a credit union. Federal credit unions cap interest at 18% on most loans, so their cards can undercut the 24% many banks charge. Check whether the card accepts balance transfers and whether it charges a fee, since some low-rate cards treat transfers like cash advances. You can also call your current issuer and ask for a lower rate, which costs nothing.
Who it suits and how to use it
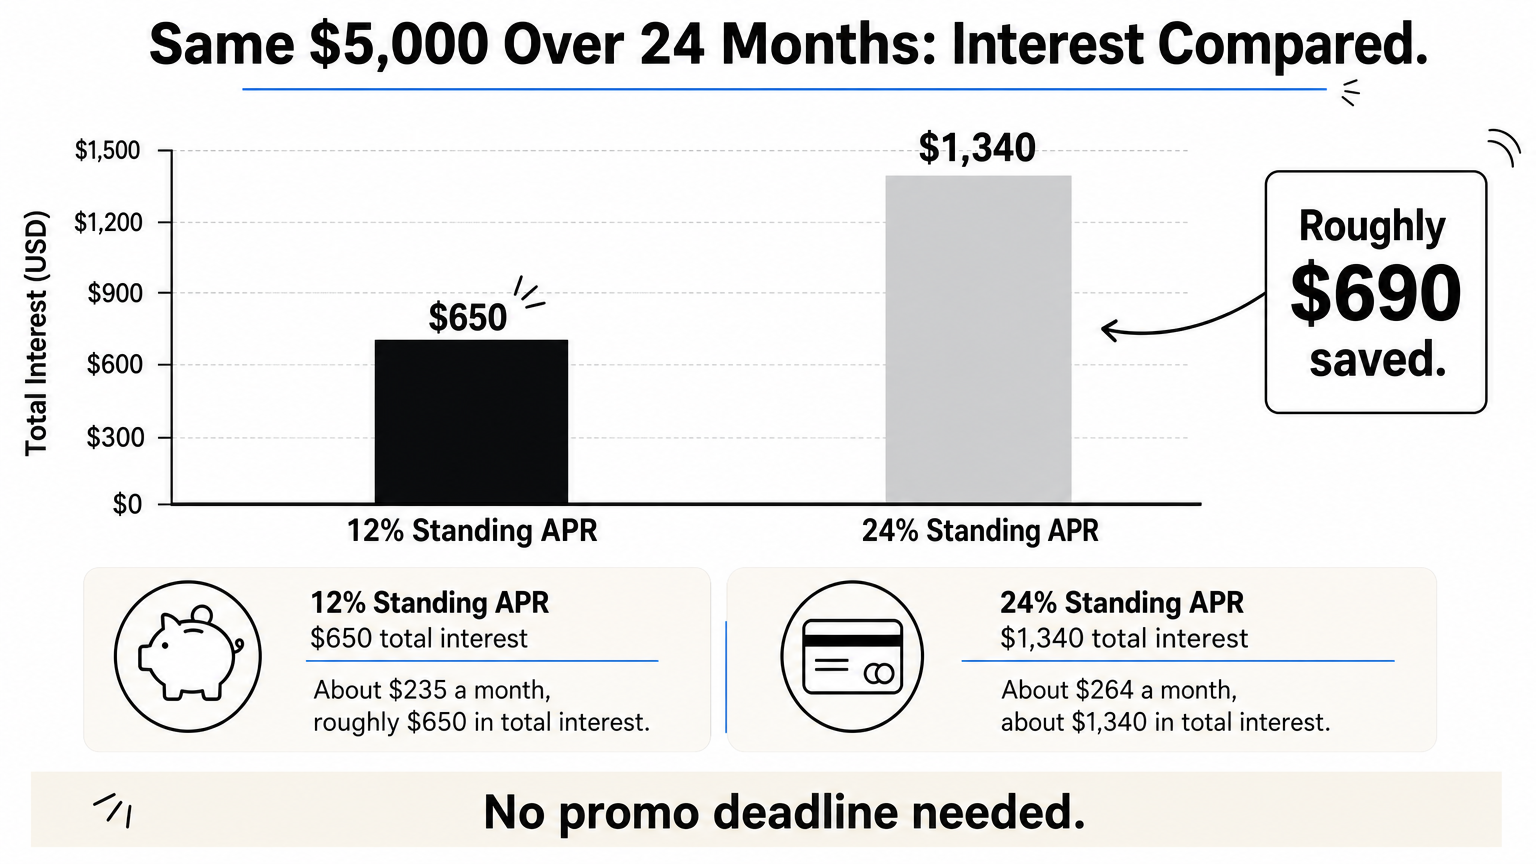
This card suits you if you have a mid-sized balance, steady income, and a plan that runs two years or more. On $5,000 repaid over 24 months, a 12% APR means about $235 a month and roughly $650 in total interest. At 24% the same plan means about $264 a month and about $1,340 in interest. That is a saving of roughly $690 without any promo deadline.
If your plan runs past two years, a low standing rate beats a promo that expires.
4. Rewards card with a 0% intro APR on transfers
A rewards card with an intro 0% on transfers and purchases ranks fourth. It works, but it tempts you to spend, and rewards rarely beat the fee and the later interest.
How it works and what it costs
These cards pair a 0% intro period with cash back or points. The trap is the regular APR, which tends to be among the highest after the promo. Rewards also rarely cover the transfer fee. On a $5,000 transfer with a 5% fee ($250), you would need to spend $12,500 at 2% back just to break even.
Who it suits and how to use it
Use one only if you are disciplined and need a card for everyday spending while you pay down debt. Put the debt on the 0% offer, pay it off on schedule, and pay each new purchase in full every month. If you tend to run balances, skip this one and pick a plain transfer card instead.
Rewards only help when you pay purchases off every month, and rewards will not clear a balance for you.
5. Secured or credit-builder card for damaged credit
A secured card will not pay off your debt, but it is the right card to hold if your score is too low for the others. It rebuilds credit while you clear the debt another way.
How it works and what it costs
You put down a refundable deposit, often a few hundred dollars, and that deposit becomes your credit limit. The issuer reports on-time payments to the credit bureaus. Expect no 0% transfer offer and a high APR, so pay the card in full each month. Be wary of "instant approval" cards advertised for debt relief, since they typically carry steep fees and rates.
Who it suits and how to use it
This card suits you if your score is low and you can’t qualify for a transfer card. Pair it with a real payoff plan, such as a nonprofit debt management plan or a personal loan. Use the secured card for one small bill, pay it on time, and watch your score climb until a transfer card becomes realistic.
When credit is damaged, use a secured card to rebuild and a debt management plan or loan to pay.
Pick the card, then run the plan
For good credit and a balance you can clear in under two years, take a long 0% transfer card and pay the balance divided by the promo months. For small balances, a low-fee card is cheaper. For longer payoffs, take a low standing APR. Use a rewards card only if you pay purchases in full, and use a secured card only to rebuild.
Whichever card you choose, the card is only the tool. The plan is what clears the debt: a fixed monthly payment, no new charges, and no missed due dates. If you want to compare transfer cards with loans and debt management plans, see the guides at Credit Card Solution.