Debt settlement law is the set of federal and state rules that govern how companies and creditors may negotiate a balance down to less than you owe. It limits what settlement companies can charge, requires certain disclosures, and protects you as a debtor. It does not force any creditor to accept a deal, and it does not shield you from collection while you negotiate.
This guide covers why those rules matter, what federal and state law require of settlement companies, and how to check a company against them before you sign. It also covers your rights when collectors call or a lawsuit arrives. It ends with the questions people ask most about settling on their own, including how much you can settle for and how forgiven debt is taxed.
Credit Card Solution is an educational site, not a settlement provider or a law firm. Think of this article as the map that helps you ask better questions. State rules differ and change, so confirm details with your state attorney general or financial regulator, and talk to a licensed attorney about your specific case.
Why debt settlement law matters to you
Debt settlement law matters because settlement is a negotiation, not a right, and the industry has a long record of charging fees for results it could not deliver. The rules are your main protection against paying for a promise.
What the law is trying to fix
Most settlement programs tell you to stop paying your creditors and deposit money into a savings account until there is enough cash to make offers. That creates real exposure. Interest and late fees keep accruing, and your credit score drops. Creditors can also sue. Lawmakers responded to the abuses that followed.
| Problem | What the law does |
|---|---|
| Fees charged before any result | The federal Telemarketing Sales Rule bans advance fees, and many states do too |
| Hidden risks | Some states require written warnings about credit damage and lawsuits |
| Money held by the company | Federal rules require the account to be yours, with free withdrawal |
| Being locked into a contract | Some states guarantee your right to cancel without penalty |
What the law cannot do
No statute obliges a creditor to accept less than the full balance. A settlement company can only ask. The New York Attorney General notes that many consumers who enroll never finish the program, and that a plan does not stop collection lawsuits.
Debt settlement law governs how the company behaves. It does not guarantee the outcome.
The law regulates the middleman. It never promises that your creditor will say yes.
What federal and state law require of settlement companies
Settlement companies answer to two layers of rules: a federal rule on fees and disclosures, plus state laws that add licensing, contract terms, and enforcement. You need to know both layers, because the stricter one usually helps you.
The federal advance-fee ban
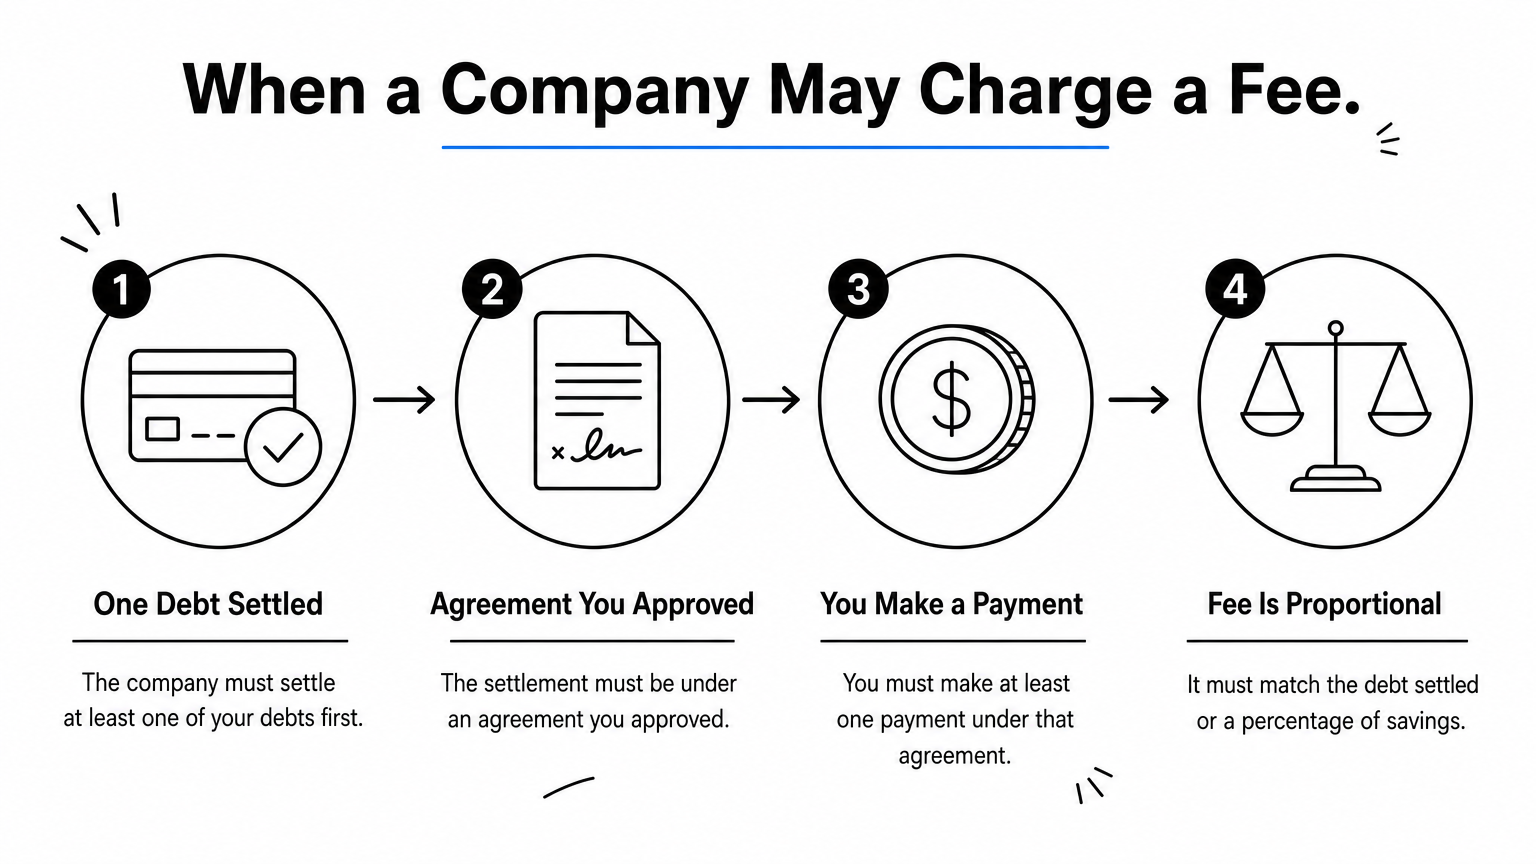
The FTC’s Telemarketing Sales Rule covers debt relief sold by phone. A company cannot collect a fee until it has settled at least one of your debts under an agreement you approved, and you have made at least one payment under that agreement. The fee must be proportional to the debt settled or a percentage of the savings.
If the company holds your money, the funds must sit in an account at an insured financial institution that you own. You must be able to withdraw without penalty. The company must also disclose how long results will take and the risks of stopping payments.
How state laws add to it
States layer their own rules on top. These examples show the range, not a full list.
| State | Example requirement |
|---|---|
| California | Fair Debt Settlement Practices Act (effective January 1, 2022): an unsigned contract at least three days before signing, cancellation anytime, monthly statements, and damages up to $5,000 in a private lawsuit |
| Maryland | Providers must register through NMLS, may not charge consultation fees, and need a $50,000 surety bond if they hold customer funds |
| New York | The Attorney General warns about advance fees and unrealistic savings plans and accepts consumer complaints |
Other states, such as Virginia, have dedicated chapters in their codes. Some states license providers, and attorneys and nonprofits are often exempt. Search your state attorney general’s website for "debt settlement" to see what applies where you live.
When federal and state rules differ, the stricter protection is the one you should expect.
How to check a settlement company against the law
You can check a company in about an hour, before you hand over a dollar. Use the list below as a screen, and walk away at the first failure.
A seven-point screen
- Check licensing. Where your state requires registration or a license, look the company up with the regulator.
- Refuse upfront fees. Any charge before a debt is settled and you have made a payment is a red flag.
- Read the contract first. Ask for a copy in advance. Look for the fee formula, the estimated timeline, and the debts covered.
- Verify the account. Money should sit in an account in your name that you can withdraw from.
- Demand the risk disclosures. A legitimate company states that results are not guaranteed and that stopping payments can hurt your credit and invite lawsuits.
- Confirm free cancellation. You should be able to leave without a penalty.
- Know where to complain. Your state attorney general, the FTC, and the CFPB take reports.
A worked fee example
Suppose you enroll $10,000 across four cards, and the contract sets a total fee of $2,000 (illustrative figures). The company settles one $2,500 card, and you make your first payment. A proportional fee for that card is $2,500 ÷ $10,000 × $2,000 = $500. If a company wants $2,000 on day one, it is breaking the model the rules describe.
Before you sign anything, ask whether a nonprofit credit counselor’s debt management plan fits your situation. It avoids many of these risks.
A company that asks for money before it has settled anything is telling you how it makes its profit.
Your rights when collectors call or a creditor sues
Your rights as a debtor exist whether or not you hire a settlement company. They cover how collectors may contact you, how you can dispute a debt, and what happens if you are sued.
Rules collectors must follow
The federal Fair Debt Collection Practices Act (FDCPA) covers third-party collectors and debt buyers. Collectors generally cannot call before 8 a.m. or after 9 p.m., harass you, lie about the amount, or threaten arrest. Regulation F also caps call attempts on a single debt.
You can dispute a debt in writing within 30 days of first contact, and the collector must verify it before contacting you again. You can also send a written request to stop contact. Neither step prevents a lawsuit. Original creditors collecting their own debt are usually outside the FDCPA, but state law still limits them. In an individual FDCPA suit, damages can reach $1,000 plus actual damages and fees.
Lawsuits and the clock
If you are served, respond, even if you think you owe nothing. A default judgment can lead to wage garnishment or a frozen bank account, and vacating one requires a court application. An attorney can help.
Every state sets a statute of limitations on suing over a debt, often three to six years, though it varies. In some states, a payment or written acknowledgment can restart it. The seven-year credit reporting period is a separate clock. After seven years a delinquency leaves your credit report, but the debt does not legally vanish.
Ignoring a summons does not make a debt go away. It hands the creditor a default judgment.
Settling on your own, and the tax catch
You can settle without a company or a court by negotiating directly and getting the deal in writing. This is often the best use of your knowledge of debt settlement law, since you skip the fees entirely.
How much and how to do it
No law sets a percentage. Some creditors accept about half or less, but none must. The right offer depends on your hardship, the account’s age, and whether a collector bought it. Offer a lump sum if you can, and get a written agreement before paying. It should state that the payment settles the account. Pay with a traceable method and keep every record.
Taxes and your credit report
Forgiven debt of $600 or more usually triggers a Form 1099-C, and the canceled amount is generally taxable income. Insolvency can exclude some of it, which you claim on IRS Form 982. A tax professional can confirm your case. Settled accounts are typically reported as "settled for less than full amount," which hurts your score less than an ongoing default but more than paying in full.
A settled debt is rarely a free pass. Plan for the tax bill and the credit mark.
What to remember about debt settlement law
Debt settlement law gives you three things: limits on what companies can charge, disclosures that expose the risks, and collector rules you can enforce. It does not guarantee a creditor’s cooperation. Check licensing, refuse upfront fees, keep your own account, and write down every agreement.
If you are weighing settlement against other routes, such as balance transfers, consolidation loans, or a nonprofit plan, start by seeing how they compare for your credit profile. You can compare your debt relief options and decide with the facts in hand.