Running a business on a credit card that charges 24% interest is a fast way to hand your profit margin to the bank. If you need to cover equipment, inventory, or a slow season without watching interest pile up, business credit cards 0 apr offers are the smartest tool available right now, letting you borrow for free during the promotional window.
The right card depends on what you need it for, and a guide to business credit cards helps you narrow the field fast. Some of the best business credit cards with 0 apr give you 12 to 18 months on new purchases, which works well if you’re financing a specific expansion. Others focus on balance transfers, letting you move existing high-interest debt over and stop the bleeding immediately, much like the top cards built for balance transfers. A few do both, and those tend to be the strongest overall picks for most owners.
Below we break down eight cards worth applying for in 2026, comparing intro periods, ongoing APRs, fees, and the credit profile each one expects from you. We’ll also flag which cards suit a business carrying debt versus one that just wants breathing room to make a big purchase, so you can match the offer to your actual situation instead of picking based on the flashiest signup bonus.
1. Chase Ink Business Unlimited® Credit Card
The Ink Business Unlimited card is the card most small business owners land on first, and for good reason. It pairs a genuinely useful 0% intro APR offer with flat-rate cash back that doesn’t require tracking bonus categories, which matters when you’re already juggling payroll and inventory orders.
0% APR offer and terms
New cardholders get 12 months at 0% APR on purchases from account opening. That’s not the longest offer on this list, but it’s paired with no annual fee, so you’re not paying to carry the promotional period. After the intro window closes, the variable APR runs in the 18.24% to 24.24% range depending on your creditworthiness. There’s no 0% balance transfer offer bundled in here, so if your goal is moving existing debt rather than financing new purchases, keep reading for cards further down this list built for that purpose.
A 12-month runway at 0% interest on everyday purchases can be the difference between a slow quarter and a cash flow crisis.
Rewards and fees
Once the intro period ends, the card keeps earning unlimited 1.5% cash back on every purchase, no category restrictions and no cap. Fees are minimal: $0 annual fee, 3% on foreign transactions, and a standard 3% (minimum $5) balance transfer fee if you do decide to move a balance. Late payment fees max out around $40, and Chase reports to all three major business credit bureaus, which helps if you’re trying to build a separate business credit card profile in your company’s name.
| Feature | Details |
|---|---|
| Intro APR | 0% for 12 months on purchases |
| Ongoing APR | 18.24%-24.24% variable |
| Annual fee | $0 |
| Rewards | 1.5% cash back, unlimited |
| Foreign transaction fee | 3% |
Who it’s best for
This card suits an owner who needs breathing room for a defined purchase, new equipment, a website rebuild, a seasonal inventory push, and wants to pay it off within a year without interest eating into margin. It’s less useful if you’re already carrying a balance elsewhere, since there’s no transfer offer to lean on.
How to qualify
Chase typically wants a good to excellent personal credit score, generally 690 or higher, since approval leans on your personal credit history alongside your business details. You’ll need your business’s legal structure, tax ID or SSN if you’re a sole proprietor, and estimated annual revenue on the application. Chase also enforces its unofficial 5/24 rule, meaning if you’ve opened five or more personal or business cards across all banks in the past 24 months, expect a denial regardless of your credit score.
2. Chase Ink Business Cash® Credit Card
The Ink Business Cash card targets a specific type of owner: someone who spends heavily on office supplies, internet, cable, phone service, and gas. If those categories dominate your monthly expenses, this card pays for the 0% period twice over through its bonus rewards structure.
0% APR offer and terms
Cardholders get 12 months at 0% intro APR on purchases from account opening, matching the Unlimited version’s offer. After that, the variable APR settles into the same 18.24% to 24.24% range based on your credit profile. There’s no annual fee, so the promotional window costs you nothing to hold onto. Like its sibling card, this one skips a 0% balance transfer offer, so it’s built for new spending rather than debt migration.
If your business runs on office supplies and utility bills, this card turns routine spending into real cash back during a year of interest-free financing.
Rewards and fees
This is where the card separates itself: 5% cash back on the first $25,000 spent annually on office supply stores, internet, cable, and phone services, then 1% after that cap. All other purchases earn 2% on the first $25,000 combined annual spend in select categories, then 1%. The $0 annual fee stays constant, foreign transactions cost 3%, and balance transfers carry the standard 3% fee.
Who it’s best for
A business heavy on recurring office and utility expenses gets more value here than from the flat-rate Unlimited card, especially if you’re also financing a specific purchase during the intro period.
How to qualify
Approval odds mirror the Unlimited card: good to excellent personal credit, typically 690+, plus the same 5/24 restriction Chase applies across its card portfolio.
3. American Express Blue Business Cash® Card
American Express built the Blue Business Cash card for owners who want simplicity: automatic cash back deposited straight to your statement, no rewards portal to log into. It’s one of the more approachable 0% apr business credit cards on this list, especially if you’re already an Amex cardholder personally.
0% APR offer and terms
Owners get 12 months at 0% intro APR on purchases from account opening, after which a variable 18.49% to 26.49% APR applies based on creditworthiness. There’s no balance transfer offer bundled in, so this card is built for new spending, not migrating old debt.
A full year of 0% financing with automatic cash back rewards is a rare combination among no-annual-fee business cards.
Rewards and fees
The card pays 2% cash back on the first $50,000 spent annually across all purchases, then 1% after that threshold. The annual fee is $0, foreign transactions cost 2.7%, and there’s no bonus-category tracking required, everything earns the same flat rate automatically.
Who it’s best for
This card fits an owner who spends broadly across categories rather than concentrating in office supplies or advertising, and who wants rewards without spreadsheets. It also suits someone who values Amex’s purchase protection and extended warranty benefits alongside the intro period.
How to qualify
American Express generally wants good to excellent credit, roughly 670 or higher, plus a clear picture of your business revenue and time in operation. Sole proprietors can apply using their Social Security number, and approval decisions often come within minutes online.
4. The Blue Business® Plus Credit Card from American Express
The Blue Business Plus card fills a gap the Blue Business Cash leaves open: Membership Rewards points instead of straight cash back, plus a longer runway before interest kicks in. If you value flexible point transfers over automatic statement credits, this is the Amex pick worth comparing first.
0% APR offer and terms
Qualifying owners get 15 months at 0% intro APR on purchases, three months longer than most cards on this list, before a variable 18.49% to 26.49% APR applies. Amex doesn’t attach a balance transfer promotion here either, so treat this as a financing tool for new spending, not a way to consolidate an existing balance elsewhere.
Three extra months of 0% financing can mean the difference between paying off a big equipment purchase in full or carrying part of it into interest charges.
Rewards and fees
Cardholders earn 2 points per dollar on the first $50,000 spent annually across all purchases, then 1 point after that. There’s no annual fee, foreign transactions run 2.7%, and points transfer to Amex’s airline and hotel partners, which gives this card more redemption flexibility than a flat cash-back structure.
Who it’s best for
Owners who travel for business or already collect Amex Membership Rewards points personally get the most mileage here, especially those planning a large purchase they want extra months to pay down.
How to qualify
Expect Amex to look for good to excellent credit, generally 670 or above, along with verifiable business revenue. Approval works the same way as the Blue Business Cash card, and sole proprietors qualify using their SSN.
5. Wells Fargo Signify Business Cash® Card
Wells Fargo’s Signify Business Cash card stands out because it doesn’t lock its best rewards rate behind spending categories, and it backs that up with one of the longer 0% windows on this list. If you want simplicity paired with real financing time, this card belongs on your shortlist of 0 apr credit cards business owners keep comparing.
0% APR offer and terms
Cardholders get 12 months at 0% intro APR on purchases from account opening, then a variable 18.24% to 28.24% APR applies based on your credit profile. Wells Fargo doesn’t pair this with a balance transfer promotion, so treat it as a tool for financing new spending rather than consolidating debt you’re already carrying elsewhere.
Flat-rate rewards mean you never have to plan your spending around a bonus category just to earn a decent return.
Rewards and fees
This card earns 2% cash back on purchases up to $50,000 spent annually, then 1% after that threshold, no enrollment or category tracking required. The annual fee is $0, and foreign transactions cost 3%. Wells Fargo also throws in a cell phone protection benefit when you pay your bill with the card, a detail that’s easy to overlook but genuinely useful for a small operation.
Who it’s best for
Owners who want predictable, uncomplicated rewards alongside a full year of interest-free financing get strong value here, especially those who’d rather not manage bonus categories across multiple cards.
How to qualify
Wells Fargo generally wants good to excellent credit, roughly 690 or higher, along with basic business revenue details. New businesses with limited history sometimes get approved based primarily on the owner’s personal credit profile.
6. Bank of America® Business Advantage Unlimited Cash Rewards
Bank of America built this card for owners already banking with them, since Preferred Rewards for Business members can boost their earning rate by up to 75% on top of the base rewards. It’s a strong pick if you keep your business checking and savings at BofA already, and it’s a flexible option among business 0 apr credit cards for owners who want a relationship discount baked in.
0% APR offer and terms
New cardholders get 9 months at 0% intro APR on purchases, shorter than most cards on this list, before a variable 18.24% to 28.24% APR kicks in. There’s no balance transfer promotion bundled here either, so this card financs new spending rather than existing debt.
A shorter intro window still works if you’re paying off a defined purchase fast rather than stretching payments across a full year.
Rewards and fees
The card earns a flat 1.5% cash back on every purchase, with no annual fee and no caps. Preferred Rewards members can push that rate to as high as 2.62% depending on their tier, which makes this card noticeably better for existing BofA business customers than for outsiders. Foreign transactions cost 3%, and standard late fees apply.
Who it’s best for
This card suits an owner already banking with Bank of America who wants a quick, defined 0% window paired with a rewards rate that scales with their existing relationship, rather than someone shopping purely on intro period length.
How to qualify
Approval typically requires good to excellent personal credit, generally 690 or above, plus verifiable business revenue and an existing or new Bank of America business account.
7. U.S. Bank Business Platinum Card
The U.S. Bank Business Platinum Card exists for one reason: the longest 0% intro window on this entire list. If you’re comparing best business credit cards 0 apr offers purely on how much time you get before interest starts, this card wins outright.
0% APR offer and terms
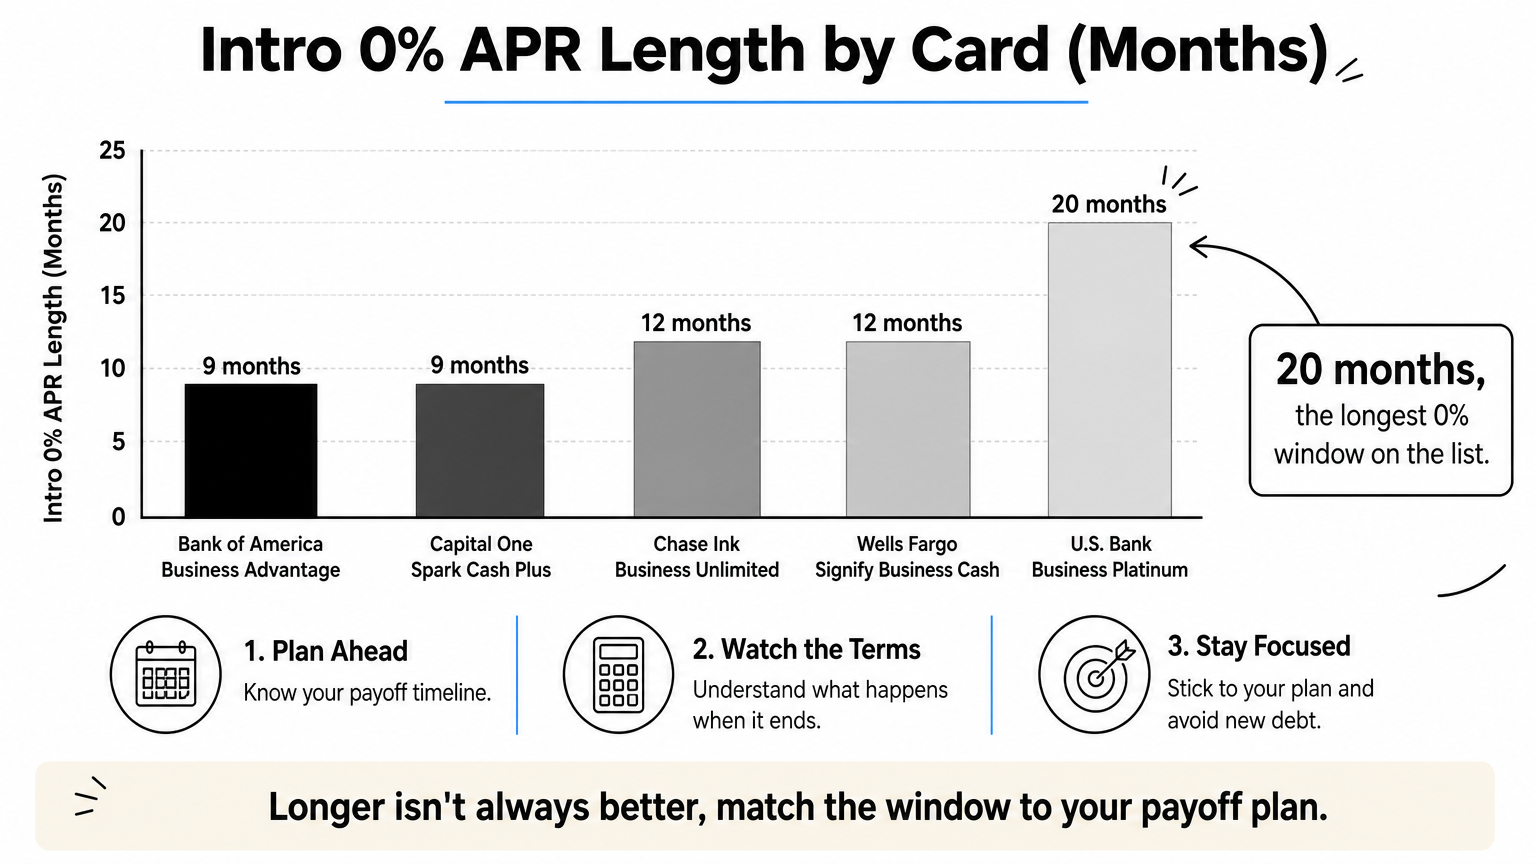
Qualifying owners get 0% intro APR for up to 20 billing cycles, roughly 18 to 20 months, on both purchases and balance transfers made within 60 days of account opening. That’s six to eight months longer than most cards above, and it’s one of the few on this list that extends the promo to balance transfers, not just new spending. After the intro period, a variable 18.24% to 28.24% APR applies. Balance transfers carry an intro fee of 3% (minimum $5).
Nearly two years of 0% financing gives you real room to pay down a large purchase or an existing balance without a single interest charge.
Rewards and fees
This card skips a rewards program entirely, no cash back, no points. The tradeoff is a $0 annual fee and a structure built purely around low-cost financing rather than earning. Foreign transactions cost 2%.
Who it’s best for
Owners carrying existing debt on another card, or planning a major purchase they need nearly two years to pay off, get more value here than from any rewards-focused card above. This is the 0 interest business credit card to reach for when time matters more than points.
How to qualify
U.S. Bank looks for good to excellent personal credit, typically 690 or higher, along with standard business revenue and structure details on the application.
8. Capital One Spark Cash Plus
Capital One built the Spark Cash Plus card for owners who want a high spending ceiling without a hard credit limit capping their operations. It’s a charge card at heart, meaning you generally pay your balance in full each cycle, but the intro financing window still gives you real room before that requirement kicks in.
0% APR offer and terms
New cardholders get 0% intro APR on purchases for 9 months from account opening, shorter than the U.S. Bank card above but still enough runway for a defined equipment purchase or inventory push. After the intro period, standard charge card terms apply, meaning you’re expected to pay your statement balance in full, so there’s no ongoing revolving APR to worry about the way there is with the other cards on this list.
A card with no preset spending limit rewards businesses that can move fast on a big purchase and pay it off on schedule.
Rewards and fees
The card earns unlimited 2% cash back on every purchase, with a $150 annual fee waived the first year. Cardholders who spend $150,000 or more annually earn a $150 bonus, and there’s no foreign transaction fee, a real advantage for businesses that buy from overseas suppliers.
Who it’s best for
This card suits an established business with strong, consistent revenue that needs flexible spending capacity more than a long revolving intro period.
How to qualify
Capital One wants excellent personal credit, typically 720 or higher, plus strong verifiable business revenue since approval depends heavily on cash flow, not just a credit score.
9. How to choose the right 0% APR business card for you
When choosing a new credit card, start by asking whether you’re financing new spending or escaping debt you already carry. That single question eliminates half this list immediately, since most business credit cards 0 apr offers only cover purchases, while only the U.S. Bank Business Platinum extends its 0% window to balance transfers. If you’re carrying a balance elsewhere at 22% interest, chasing rewards on a purchase-only card is the wrong move.
Next, match the intro period length to your actual payoff timeline, not the longest number you can find. A 9-month window works fine if you’re paying off a $6,000 equipment purchase in manageable chunks. A 20-month window matters more if you’re doing credit card debt consolidation on $15,000 in existing balances spread across multiple cards.
Pick the card that matches how long you actually need, not the one with the flashiest headline number.
Use this quick checklist before applying:
- Debt or new spending? Determines whether you need a balance transfer offer at all
- Payoff timeline Match it to the intro period, with a buffer of one or two months
- Spending pattern Flat-rate cards suit broad spenders, category cards suit concentrated expenses
- Credit profile Most cards want 670-690+, Capital One Spark Cash Plus wants 720+
- Banking relationship Existing Bank of America or Amex customers may unlock better effective rates
Finally, run the math on fees. A 3% balance transfer fee on a $10,000 transfer costs $300 upfront, still far cheaper than a year of 22% interest, but worth confirming before you assume the offer is free money.
Putting your 0% APR period to work
A 0% intro period only pays off if you treat it like a deadline, not a grace period. Write down the exact month your rate jumps, whether that’s 9 months out or 20, and build a payoff plan that clears the balance before then. Business credit cards 0 apr offers are free financing, but only if you actually stop the clock before interest starts.
Compare the eight cards above against your real numbers: your payoff timeline, your spending pattern, and whether you’re financing new purchases or escaping debt that’s already costing you. The right 0% interest business credit card isn’t the one with the longest headline number, it’s the one that matches how you actually run your business.
If you’re still carrying high-interest balances while you sort out which card fits, don’t wait to start cutting that cost. Get the credit card solution that fits your business and start cutting what that debt costs you before it grows.