You need your score higher, and you need it soon. Maybe a mortgage lender is asking for a 20-point bump, or you got denied for a card and want to know why. Whatever the reason, searching for credit score improvement services usually means you’re past the point of reading generic tips and ready to actually act.
Here’s the direct answer: a handful of tools and services move the needle faster than the rest, and most of them cost nothing. Free options like Experian Boost can add points within days by crediting your utility and streaming payments, while legitimate credit repair companies dispute errors that are quietly dragging your score down. The trick is knowing which service fits your specific situation instead of trying everything at once.
This list breaks down the 7 best options available right now, ranked by how fast they work and who they actually help. You’ll see free tools for quick wins, paid services for deeper credit report cleanup, and a few methods most people overlook entirely. By the end, you’ll know exactly where to start based on your credit history and how much time you have.
1. Experian Boost for instant, free score gains
Experian Boost sits at the top of this list because it does something almost no other tool can: it adds positive payment history to your credit file in real time, for free. If you’re asking how to raise credit score quickly without paying a dime or waiting months, this walkthrough on raising your credit score is where you start. It works by scanning your bank account for recurring bills you’re already paying on time, things like Netflix, your phone bill, or your electric company, and adding them to your Experian credit report as evidence of responsible payment behavior.
How it works
You connect your checking account or debit card statements through Experian’s secure portal, and the tool identifies eligible on-time payments going back up to 24 months. Once you approve which accounts to include, Experian recalculates your FICO Score based on the FICO Score 8 model, plus a couple of newer versions lenders are starting to use. The catch is that this only affects your Experian file, not your Equifax or TransUnion reports, so a lender pulling from a different bureau won’t see the bump.
Experian Boost is the fastest legitimate way to see your score change, sometimes within minutes of connecting your account.
Who it’s best for
This service works best for people with thin credit files or a short credit history, since it gives you extra positive data points to work with. It’s also useful if you’re wondering how can you raise credit score fast ahead of a specific application deadline, like a car loan or apartment lease that only checks Experian. Renters who pay their bills reliably but have never had that discipline reflected in their score see some of the biggest average gains, often in the 10 to 15 point range according to Experian’s own reporting.
Cost
Experian Boost is completely free, and there’s no premium tier required to get the score bump itself. Experian does upsell subscription products like Experian CreditWorks or identity monitoring during the sign-up flow, but you can decline all of that and still get the boost. No credit card is required to activate the feature, which separates it from most other credit score improvement services on this list.
How fast you’ll see results
Most users see an updated score within a few minutes of linking their bank account, since Experian processes the eligible payments almost instantly. That said, the size of the increase depends heavily on how many qualifying bills you have and how consistently you’ve paid them. Here’s a quick breakdown of what to expect:
| Factor | Typical Impact |
|---|---|
| Thin credit file (under 2 years) | Larger boost, often 10-15+ points |
| Established credit history (5+ years) | Smaller boost, sometimes 0-5 points |
| Utility and phone bills only | Modest gain |
| Utility, phone, and streaming combined | Higher gain |
If your file is already thick with accounts, don’t expect miracles. Experian Boost is a genuine tool, not a shortcut around a history of missed payments or high credit utilization, so anyone hoping to raise a credit score 300 points will need more than this one feature.
2. Credit Saint for comprehensive credit repair
Credit Saint takes a different approach than Experian Boost. Instead of adding positive data, it goes after the negative items already hurting you, late payments, collections, charge-offs on your credit report, and errors that shouldn’t be there in the first place. If you’ve pulled your credit report and found mistakes you don’t recognize, this is one of the more established credit score improvement services built specifically for that cleanup work, though it’s fair to first ask whether credit repair services are reliable.
How it works
After you sign up, Credit Saint pulls your reports from all three bureaus and assigns you a case with dedicated credit specialists. They challenge inaccurate, outdated, or unverifiable items directly with Equifax, Experian, and TransUnion, using certified mail and documented dispute letters rather than generic online forms. You get a client portal to track which items are disputed, which bureaus responded, and what got removed.
Credit Saint doesn’t touch accurate negative information, it targets the errors bureaus can’t legally verify.
Who it’s best for
This service suits people with several disputable items across multiple reports who don’t have the time or patience to write dispute letters themselves. If you’re searching for how to raise a credit score fast after identity theft or a billing error snowballed into multiple collection accounts, Credit Saint’s three-tier packages give you a structured path forward.
Cost
Credit Saint charges a setup fee between $99 and $195, then monthly fees ranging from roughly $79.99 to $119.99 depending on the package. There’s no fixed contract length, and you can cancel anytime, though most clients stay enrolled for several months to work through multiple dispute rounds.
How fast you’ll see results
Expect your first round of dispute results within 30 to 45 days, since that’s the window the Fair Credit Reporting Act gives bureaus to respond. Full cleanup for complicated files often takes four to six months across multiple rounds. Don’t expect overnight jumps here; this is steady, documented progress, not an instant score bump.
3. The Credit People for budget-friendly disputes
The Credit People built its reputation on flat-rate pricing at a time when most competitors charge per bureau or per deleted item. If you’ve compared credit score improvement services and felt priced out, this is the option that keeps costs predictable while still going after the same inaccurate accounts dragging your score down.
How it works
Once you enroll, The Credit People pulls your three-bureau reports and identifies items worth disputing, things like collections past the statute of limitations, duplicate accounts, or late payments that don’t match your own records. Their team sends dispute letters directly to Equifax, Experian, and TransUnion, then follows up as bureaus respond within their legal windows. You get phone and online access to check progress, though the portal is less polished than some pricier competitors.
The Credit People proves you don’t need premium pricing to get real dispute results.
Who it’s best for
This service fits people who know exactly what needs disputing but don’t want to pay Credit Saint or Lexington Law rates for the same basic process, so it helps to compare the top credit repair companies side by side first. It’s also a solid match if you’re asking how do you raise credit score fast on a tight budget, since the flat monthly fee covers unlimited disputes rather than charging you per item removed. Anyone managing several errors across all three bureaus gets more value here than someone with just one or two accounts to fix.
Cost
The Credit People charges a flat rate around $79 to $99 per month for individuals, with a couples plan available for roughly $20 to $30 more. There’s no setup fee in most cases, and you can cancel month to month without a long-term contract locking you in.
How fast you’ll see results
Expect initial bureau responses within the standard 30 to 45 day dispute window, similar to other credit repair companies. Most clients see their first round of deletions within two to three months, with continued cleanup over four to six months for more complicated files. Sticking with the process matters more than speed here; premature cancellation means unresolved disputes stall out.
4. Sky Blue Credit Repair for best overall value
Sky Blue Credit Repair earns its spot here because it pairs affordable pricing with a pace of dispute activity that rivals companies charging twice as much, the kind of work laid out in this complete guide to credit repair. Unlike The Credit People’s flat rate, Sky Blue disputes multiple items per round for both you and a spouse or family member under one plan, which makes it one of the more efficient credit score improvement services for households tackling debt together.
How it works
Sky Blue pulls your reports from all three bureaus and challenges inaccurate items in batches of up to 15 per round, rather than trickling out one dispute at a time. Their team also sends goodwill letters to creditors asking them to remove late payments as a courtesy, something many competitors skip entirely. You get a client dashboard showing dispute status, and phone support if you’d rather talk through your file than read updates online.
Sky Blue moves faster per dollar than almost any other credit repair company on this list.
Who it’s best for
Couples or family members dealing with credit damage together get the most value here, since the plan covers two people for one combined fee. If you’re looking for raise credit score tips that don’t require managing separate accounts and separate bills, Sky Blue simplifies that. It also suits anyone who wants aggressive dispute volume without paying premium per-person rates.
Cost
Sky Blue charges a flat $79 per month per person, or roughly $119 for two people on the same plan, with a $79 first-work fee. There’s a 90-day money-back guarantee if you don’t see items removed, which few competitors offer outright.
How fast you’ll see results
Because Sky Blue disputes items in larger batches, many clients report seeing their first deletions within 30 to 45 days. Full results for multiple negative items typically land within three to five months, putting it slightly ahead of pace compared to slower, single-item dispute services.
5. Nonprofit credit counseling for debt management
Nonprofit credit counseling agencies take a completely different route than the credit repair companies above. Instead of disputing items on your report, a certified counselor looks at your entire financial picture, income, debts, and spending, then builds a debt management plan that lowers your interest rates and handles credit card debt consolidation by rolling your payments into one monthly bill. If your score is suffering because you’re drowning in high-interest balances rather than reporting errors, this is one of the more overlooked credit score improvement services available.
How it works
You meet with a counselor from an agency accredited by the National Foundation for Credit Counseling, who pulls your credit report and negotiates directly with your card issuers on interest rates, a process worth understanding through this breakdown of how credit counseling works. Most issuers agree to cut APRs to single digits for accounts enrolled in a formal plan, which speeds up payoff and improves your credit utilization ratio, one of the biggest factors in your score.
Lowering your utilization through a debt management plan often does more for your score than any dispute letter ever could.
Who it’s best for
This path suits anyone carrying revolving balances above 30% of their available credit, especially if you’re behind on payments or juggling multiple card issuers. It’s a strong fit if you’re less concerned with how to instantly raise credit score and more focused on fixing the underlying debt causing the damage.
Cost
Nonprofit counseling sessions are typically free or cost around $25 to $50 to set up, with a small monthly maintenance fee near $25. Compare that against the $99 to $195 setup fees charged by credit repair companies like Credit Saint above, and the value here is hard to ignore.
How fast you’ll see results
Scores often dip slightly when accounts close under the plan, then climb steadily over 12 to 24 months as balances drop and utilization improves. It’s slower than Experian Boost, but the gains tend to stick.
6. DIY credit report disputes to fix errors yourself
Nothing on this list costs less than doing the work yourself, and for a lot of readers that’s the smartest move before paying anyone else. Every consumer has the legal right to dispute inaccurate information directly with the bureaus, and the process isn’t complicated once you know the steps. If you’re comfortable with paperwork and follow-up, this is one of the most direct credit score improvement services because it puts you in control of every letter.
How it works
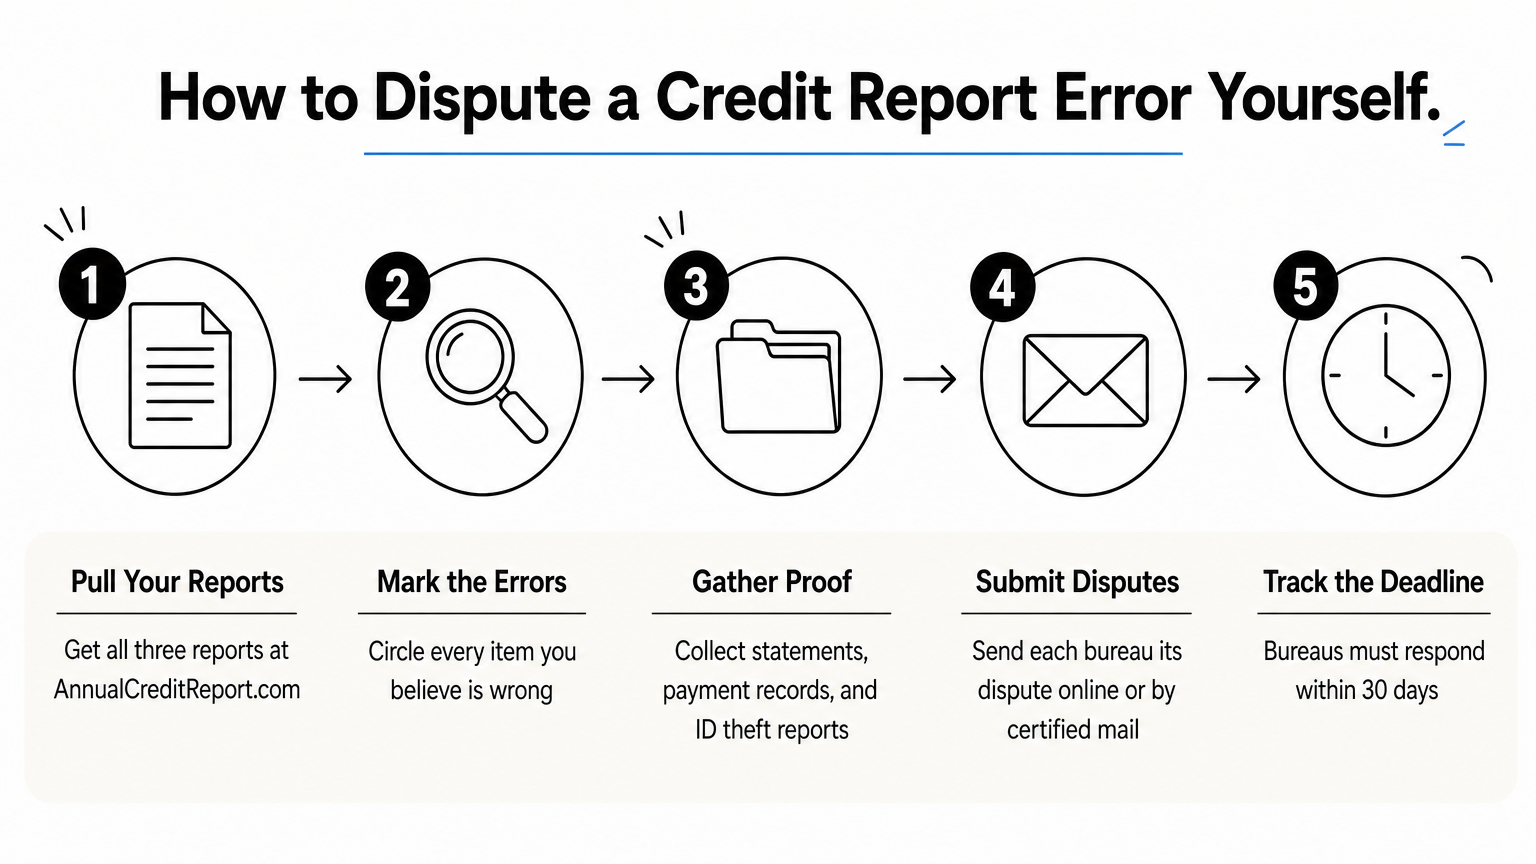
Start with a free credit score check and pull your reports at AnnualCreditReport.com, then flag anything wrong: accounts you don’t recognize, late payments that don’t match your records, or balances reported incorrectly. From there, you file disputes with each bureau that shows the error, and a credit dispute letter sample makes the wording easy to get right.
1. Pull all three reports at AnnualCreditReport.com
2. Circle every item you believe is wrong
3. Gather proof: statements, payment confirmations, ID theft reports
4. Submit disputes online or by certified mail to each bureau separately
5. Track the 30-day response window per the Fair Credit Reporting Act
A dispute letter you write yourself carries the same legal weight as one from a paid credit repair company.
Who it’s best for
This route suits anyone with only one or two disputable items, or anyone asking how to raise a credit score quickly without a monthly fee eating into their budget. If you have organized records and a little patience, you don’t need to outsource work you can finish in an afternoon.
Cost
Disputing directly with the bureaus costs nothing. You’ll spend a bit on certified mail if you skip the online forms, usually under $10 total for all three bureaus combined.
How fast you’ll see results
Bureaus must investigate within 30 days, sometimes 45 if you submit extra documentation late. Simple, well-documented errors often get corrected within that first cycle, making this one of the faster credit score improvement service options for anyone willing to do the legwork.
7. Secured cards and credit-builder loans to build history
Sometimes your score isn’t low because of errors or debt, it’s low because you simply don’t have enough payment history for the bureaus to score confidently. If that’s you, no dispute letter or counseling session fixes the problem. What you need is new, positive activity reported every month, and that’s exactly what secured cards and credit-builder loans deliver. Both belong on any honest list of credit score improvement services because they build the foundation everything else depends on.
How it works
How a secured credit card works is simple: a refundable deposit, usually $200 to $500, becomes your credit limit. You use it like a normal card and pay it off monthly, and the issuer reports that activity to all three bureaus. A credit-builder loan flips the order: the lender holds your loan amount in a locked account while you make fixed monthly payments, then releases the funds once you’ve paid it off. Both methods report on-time payments, which matters more than almost any other factor in your score.
Payment history makes up 35% of your FICO Score, and secured products exist purely to build that history from scratch.
Who it’s best for
These tools fit people with no credit file, a recently damaged one after closing old accounts, or anyone rebuilding after a bankruptcy discharge, the same group served by credit cards for people with bad credit. If you’re asking how to raise a credit score fast but have nothing on your report worth disputing, this is your realistic starting point instead.
Cost
Secured cards range from $0 annual fees to around $35, plus your refundable deposit, with options like the OpenSky secured Visa credit card sitting near the low end. Credit-builder loans typically charge $8 to $15 in interest and fees monthly through lenders like Self or local credit unions.
How fast you’ll see results
Expect your first reported payment to appear within 30 to 60 days, which is roughly how you build your credit score in 6 months of consistent payments. A full year of on-time payments builds a file lenders trust.
Finding the right fit for your credit goals
No single service fixes every credit problem, and that’s the real takeaway here. Experian Boost works fastest for thin files, credit repair companies like Credit Saint or Sky Blue tackle report errors, nonprofit counseling handles high utilization, and secured cards build history from nothing. The honest move is matching the tool to the actual reason your score is low instead of guessing.
Start by pulling your three reports and being blunt with yourself about what you see: errors, debt, or just a lack of history. That answer points you straight to the right option on this list, and often more than one applies at once. Combining a few of these credit score improvement services usually beats relying on just one.
If you’re still untangling which strategy fits your situation, or you want a broader plan for tackling the debt behind a damaged score, find the right credit card solution before you commit a dollar to any service.